What are CHOICE Arrangements? A Simple Guide to Custom Health Option and Individual Care Expense Arrangements.
You may have heard about Custom Health Option and Individual Care Expense Arrangements, or CHOICE Arrangements (formerly known as ICHRAs), which are quickly becoming a popular alternative to typical group health coverage. Here’s what you need to know.
What is a CHOICE Arrangement?
A CHOICE Arrangement is a health benefit model where an employer reimburses employees for their individual health insurance premiums and other qualified medical expenses related to coverage they select. With CHOICE Arrangements, individuals choose the health plan that meets their personal needs and budget instead of selecting from a predetermined set of group health plan options. While this approach differs from traditional group health insurance, it offers comprehensive coverage for the same essential health benefits.
How do CHOICE Arrangements work?
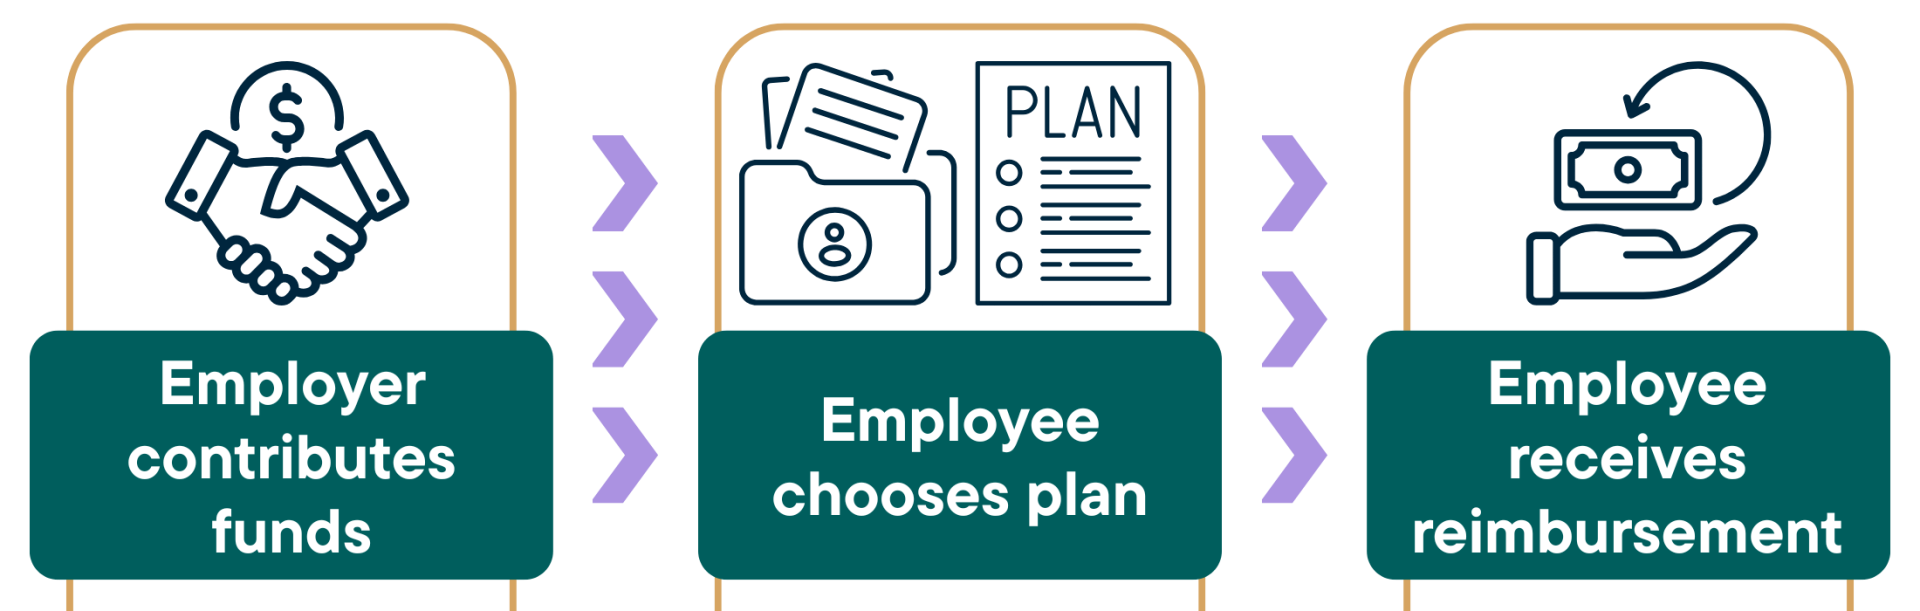
With a CHOICE arrangement, the employer provides a set dollar amount for each employee to utilize toward health insurance premiums and certain medical expenses. Generally, the employer pre-funds the employee’s HRA with the contribution amount. Employees are then able to shop for individual health coverage - a Marketplace plan or a private plan outside the Marketplace - that best fits their situation and desired level of coverage. The ability to shop for their own health coverage means that employees have access to extensive benefits, providers, and health networks. Another perk of the CHOICE Arrangement model is that employees own their health plan and take it with them if they change jobs, ensuring continuous coverage.
It’s important to know that CHOICE Arrangements provide flexibility and autonomy to employees, but also the added responsibility of choosing and enrolling in a plan within the specified Open Enrollment Period (Nov. 1 – Jan. 15) or Special Enrollment Period (varies based on situation). In addition, employees need to be careful to select coverage that includes their preferred doctors and facilities.
Employees are responsible for paying any remaining premium costs beyond the amount allotted by their employer. After an employee selects a health plan, the employer typically deducts the premium balance from the employee’s paycheck on a pre-tax basis.
If this process sounds a bit confusing, know that you’re not alone. The RetireMed team is here to help you navigate CHOICE Arrangements, whether you’re an employee looking for coverage to fit your needs or an employer looking into a CHOICE Arrangement as a possible health benefit option.
Who can offer a CHOICE Arrangement and who is eligible?
Any size or type of employer can offer a CHOICE Arrangement instead of a group health plan to employees. However, employees have certain eligibility requirements they must meet to participate in a CHOICE Arrangement.
If an employee would like to participate in their employer’s CHOICE Arrangement program, they (along with eligible household members) must obtain health coverage – either an individual health plan or a Medicare plan (either Medicare Advantage or Medicare Supplement) - that begins at least by the time the CHOICE Arrangement starts. Employees may opt out of their employer’s CHOICE Arrangement if they choose.
Employers are not permitted to offer employees the option between a group health plan and a CHOICE Arrangement. Also, an employee cannot enroll in a group health plan if they have a CHOICE Arrangement, and they can’t participate in a CHOICE Arrangement if they’re enrolled in a group health plan.
CHOICE Arrangements vs. Other Health Benefit Options
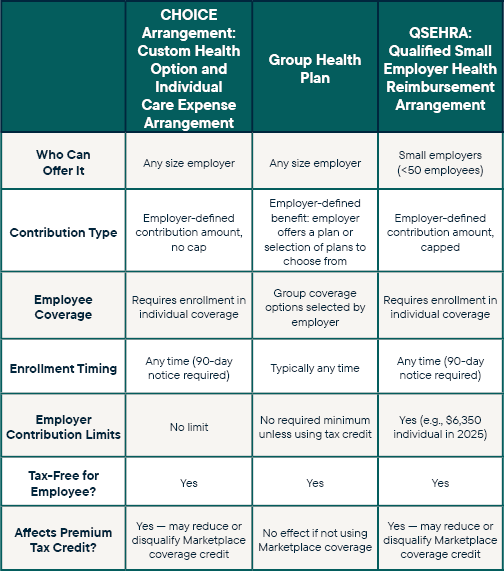
So, how does a CHOICE Arrangement compare to other forms of employer health coverage, such as group health insurance and QSEHRA (Qualified Small Employer Health Reimbursement Arrangement)? See our chart.
CHOICE Arrangement vs. HSA
CHOICE Arrangement: A Custom Health Option and Individual Care Expense Arrangement is a benefit model where the employer offers employees pre-tax dollars for medical expenses such as premiums, deductibles, and copayments. The funds can be used to purchase a Marketplace (ACA) or Medicare plan (Medicare Advantage or Medicare Supplement).
HSA: An HSA or Health Savings Account is a type of savings account that allows individuals to set aside money on a pre-tax basis for qualified medical expenses. Unlike CHOICE Arrangements, funds in an HSA generally cannot be used to pay insurance premiums.
How CHOICE Arrangements Affect Premium Subsidies
With a CHOICE Arrangement, individuals purchase individual or Medicare coverage. In the case of individual Marketplace (ACA) coverage, the monthly cost is individualized and based on the estimated income of all household members. Many households qualify for a tax credit, which is a subsidy based on household size and income. This tax credit could reduce your monthly insurance premium for a Marketplace plan. However, if you participate in a CHOICE Arrangement, you will not qualify for a premium tax credit if your CHOICE Arrangement is considered “affordable” based on government-mandated standards. Learn more about affordability.
Affordability rules can be complex but are important to be aware of when shopping for an individual health insurance plan, which is why we strongly recommend working with a health insurance advisor who knows the ins and outs of CHOICE Arrangements and can help you review ideal options for your needs.
How RetireMed Can Help
Whether you’re an employee trying to figure out how CHOICE Arrangements work or an employer considering if a CHOICE Arrangement would be a good fit for your company, we’re here to help. Our deep understanding of plan options, regulations, and best practices ensures that you will receive the CHOICE Arrangement expertise you need. Call our team today!
Share This Article